







1099 NEC vs 1099 MISC
Both forms report money your business paid out, but they cover different payment types. Use the NEC for contractor services, and the 1099-MISC for rents, royalties, prizes, awards, and legal settlements.
| Form 1099-NEC | Form 1099-MISC | |
|---|---|---|
| What it reports | Nonemployee compensation for services | Rents, royalties, prizes, awards, attorney payments |
| Who receives it | Contractors, freelancers, consultants | Landlords, royalty recipients, attorneys |
| IRS deadline | January 31 | February 28 on paper, March 31 electronically |
The 1099 misc vs 1099 nec question comes up because the two used to be one form. Before 2020, contractor payments went in Box 7 of the 1099-MISC; that box now reports direct sales of $5,000 or more. For a fuller side-by-side, see how the 1099-MISC and 1099-NEC differ.
The 2026 Threshold Change: $600 to $2,000
This is the detail most likely to trip you up this season, because the number moved. For payments made in tax year 2025 and earlier, the threshold is $600. The One Big Beautiful Bill Act, signed in July 2025, raised it to $2,000 for payments made after December 31, 2025, indexed for inflation from 2027.
| Payments made in | Reporting threshold |
|---|---|
| Tax year 2025 and earlier | $600 or more |
| Tax year 2026 | $2,000 or more |
| Tax year 2027 onward | $2,000, indexed for inflation |
In practice: say you pay a freelance bookkeeper $1,800 over the year. For 2025 that sits above the $600 line, so a 1099-NEC is required. For 2026 the same $1,800 falls below the $2,000 line, so it is not. Confirm which tax year you are filing for before deciding who gets a form.
1099 NEC Instructions: A Box-by-Box Breakdown
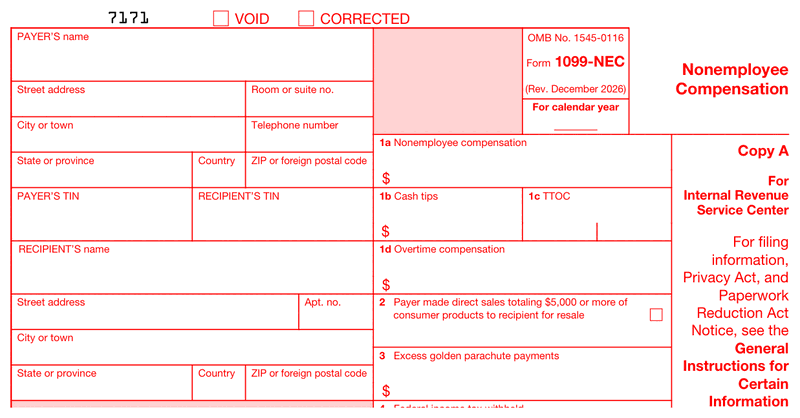
The form is short. Most businesses fill in three fields and leave the rest empty.
| Box | Label | What goes in it |
|---|---|---|
| Box 1a | Nonemployee compensation | Total gross paid for services during the year: fees, commissions, prizes, awards |
| Box 1b | Cash tips | Cash tips reported by the recipient, if any |
| Box 1c | Treasury tipped occupation code | The Treasury tipped occupation code, used when reporting cash tips |
| Box 1d | Qualified overtime compensation | Qualified overtime compensation, if any |
| Box 2 | Direct sales | Check it if you sold $5,000 or more in consumer products to the recipient for resale |
| Box 3 | Excess golden parachute payments | Excess golden parachute payments, moved here from Form 1099-MISC |
| Box 4 | Federal income tax withheld | Usually blank; used only when backup withholding at 24% applies |
| Box 5 | State tax withheld | State income tax withheld, if any |
| Box 6 | State/Payer's state no. | Your state tax identification number |
| Box 7 | State income | The portion of the payment that is state-taxable |
Box 1a carries the weight. Nonemployee compensation meaning, in plain terms, is what you paid someone for work performed who is not your employee, also written as non employee compensation. Report the gross figure, before any expenses the contractor deducts on their own return.
Before you start, have three things ready: your business name, address, and EIN; the recipient's legal name, address, and TIN from their W-9; and the payment total for the year. The 1099-NEC instructions are short, but a wrong TIN causes more trouble than any other error on the form, so check it against the W-9 before you file.
1099 NEC Deadlines
January 31 is the date for both copies. Send Copy B to the contractor and file Copy A with the IRS by January 31, whether you file on paper or electronically. If January 31 falls on a weekend or holiday, the deadline shifts to the next business day.
That is worth stating plainly, because this form does not follow the same calendar as the rest of the 1099 family. Other 1099 forms give you until February 28 on paper, or March 31 electronically, for the IRS copy. The NEC does not, and it has no automatic 30-day extension. Treat January 31 as firm.
How to File a 1099 NEC
Filing is a repeatable workflow once the details are in hand:
- Collect a signed W-9 from every contractor before the first payment. It gives you their legal name and TIN.
- Verify the TIN is present and correct. For a business payee, you can look up their EIN to confirm it.
- Total each contractor's payments for the tax year and compare against that year's threshold.
- Prepare the form, entering the payment total in Box 1a and any withholding in Box 4.
- Send Copy B to the recipient and file Copy A with the IRS, both by January 31.
You can file form copies on paper or electronically, but e-filing becomes mandatory sooner than most owners expect. File 10 or more information returns for the year, counting W-2s and 1099s together, and you must e-file through IRIS, which is the sole intake system from filing season 2027 now that FIRE has retired. and you must e-file through IRIS or FIRE. Starting each contractor with a fillable W-9 makes every later step easier.
Create a 1099 NEC Online
You do not need preprinted red-ink stock or accounting software to produce a clean, compliant form. Our 1099 NEC generator handles the layout and the math on screen:
- Enter your business details as the payer: name, address, and EIN.
- Enter the recipient's details from their W-9, including their TIN.
- Enter the Box 1a payment total and any federal income tax withheld.
- Preview the finished form and check every field.
- Download a print-ready PDF, send Copy B, and keep your copy on file.
A small business owner issuing six forms in January should not lose an afternoon to formatting. Preview free and pay only when you download, with no subscription. If you also run payroll for W-2 staff, our pay stub templates handle that in the same place, and our 1099 generator guide covers the other form types.
Backup Withholding and Missing TINs
Backup withholding is what happens when you cannot verify who you are paying. If a contractor does not furnish a TIN, or the number they give you does not match IRS records, you must withhold a flat 24% from their payments and send it to the IRS.
You report the amount withheld in Box 4, and the withholding itself on Form 945. That is two extra filings, plus an awkward conversation with a contractor whose check just shrank by a quarter.
The fix costs nothing and takes one email. Get a completed W-9 before the first payment, not after the work is done. Once the money has changed hands, your leverage to collect a TIN is gone.
Penalties and How to Correct a Filed 1099 NEC
Late and incorrect filings carry per-form penalties that scale with how late you are. For returns due in 2026:
- $60 per form if you file within 30 days of the deadline
- $130 per form if you file more than 30 days late but by August 1
- $340 per form if you file after August 1 or not at all
- At least $680 per form where the IRS finds intentional disregard
Multiply any of those by a dozen contractors and the arithmetic turns uncomfortable fast.
If you spot an error after filing, submit a corrected 1099-NEC promptly. A mismatched name or TIN can generate a CP2100 or CP2100A notice, which starts a clock on soliciting a corrected W-9 and possibly beginning backup withholding. Fixing it yourself is far less work than answering the notice.
What If You Get Both a 1099 NEC and a W-2?
Report both on the same tax return. Your W-2 wages already had income tax, Social Security, and Medicare withheld, but your 1099-NEC income did not. That contractor income is subject to self-employment tax and may require quarterly estimated payments.
This comes up on both sides of a small business: an owner may take contract work while drawing a salary, and the contractors you pay often hold a day job. Nothing was withheld from the contractor portion, so that tax bill arrives in one lump unless it gets paid along the way.
Two habits help. Set aside a percentage of every contractor payment as it arrives, and check whether quarterly estimated taxes apply. Contractors can also offset the income with legitimate business deductions, which lowers the self-employment tax base.
Which 1099-NEC Revision Do You Need?
There is no annual Form 1099-NEC. The IRS issues it as a continuous-use form, with instructions telling filers to continue using the current revision for subsequent years until a superseding revision is issued. So when you search for a 1099 NEC form 2025 or a 1099 NEC form 2026, the year refers to the tax year of the payments you are reporting, not to two different documents.
What you match is the revision, not the year on your calendar. Use the December 2026 revision to report tax year 2026 payments when you file in early 2027, and the earlier revision for tax year 2025. Do not apply the December 2026 revision to a prior year: it is not interchangeable with the one before it.
Three changes in the December 2026 revision affect whoever prepares your forms. Box 1b now reports cash tips and box 1c the Treasury tipped occupation code, with box 1d for qualified overtime compensation. Box 3 carries excess golden parachute payments moved off Form 1099-MISC. Payer and recipient address fields are split into individual entry boxes.
Two dates for your calendar: tax year 2025 forms were due February 2, 2026, and tax year 2026 forms are due February 1, 2027, recipient copy and IRS copy alike. Note also that FIRE is retired for tax year 2026, leaving IRIS as the sole intake system for filing season 2027.