


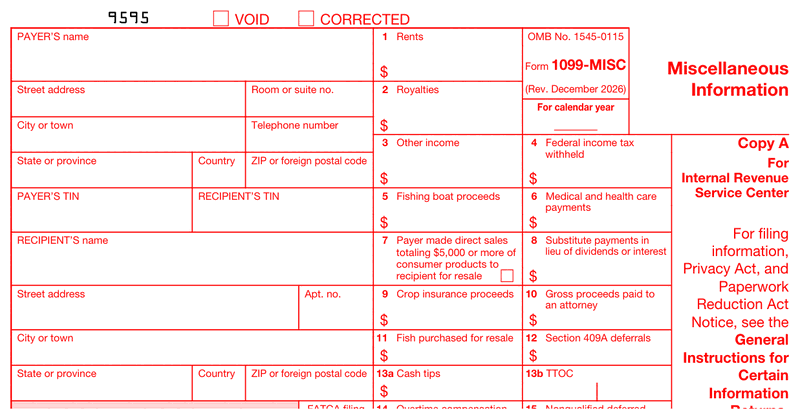





1099-MISC or 1099-NEC — Which One Do I File?
Ask what the payment was for. Payment for services performed by a non-employee is nonemployee compensation and belongs on the NEC. Payment that is not for services — rent, a prize, a legal settlement — belongs on the MISC.
Some businesses file both in the same year, for the same person. A landlord-contractor who also fixed your office plumbing gets a MISC for the rent and an NEC for the repair work. The forms coexist; the income types do not mix.
Which Boxes Matter Most?
Box 1 is rents. Box 2 is royalties, with its lower $10 threshold. Box 3 is the catch-all "other income" — prizes, awards and taxable damages. Box 6 covers medical and health care payments, and Box 10 covers gross proceeds paid to attorneys.
Most filers use one or two boxes and leave the rest empty. The generator only asks about the ones that apply to you, and the preview shows exactly where each figure lands on the official layout.
What Happens If I Skip Filing?
The IRS matches information returns against recipients' tax returns, so a missing MISC is visible from both directions. Penalties are charged per form and rise the longer the form stays unfiled.
Filing late still beats not filing. If January has passed, create and send the form anyway — the penalty tiers reward catching up early.
Attorney Payments — MISC or NEC?
Both forms touch lawyers, in different ways. Fees paid to an attorney for legal services are nonemployee compensation and go on the 1099-NEC, like any other contractor.
Gross proceeds paid to an attorney — a settlement check routed through a law firm, for example — go in Box 10 of the MISC. The distinction is what the money was: payment for the lawyer’s work, or money passing through the lawyer’s hands.
What About Backup Withholding on a MISC?
Box 4 exists for it. If a payee never provided a valid TIN, the payer must withhold 24% of reportable payments and remit it to the IRS — and the withheld amount is reported in Box 4 of the MISC.
The fix is upstream: collect a completed W-9 from every payee before money moves. Backup withholding is an administrative burden for the payer and an unwelcome surprise for the payee; a one-page form prevents both.
How Do the Thresholds Work Across Many Small Payments?
Per payee, per year, in total. Rent of $100 a month is $1,200 by December — reportable, even though no single payment came near $600. The ledger decides, not the check size.
The same aggregation applies to every MISC box, each against its own threshold: $600 for rents and most others, $10 for royalties. A year-end pass over the payee ledger is what catches the quiet qualifiers.